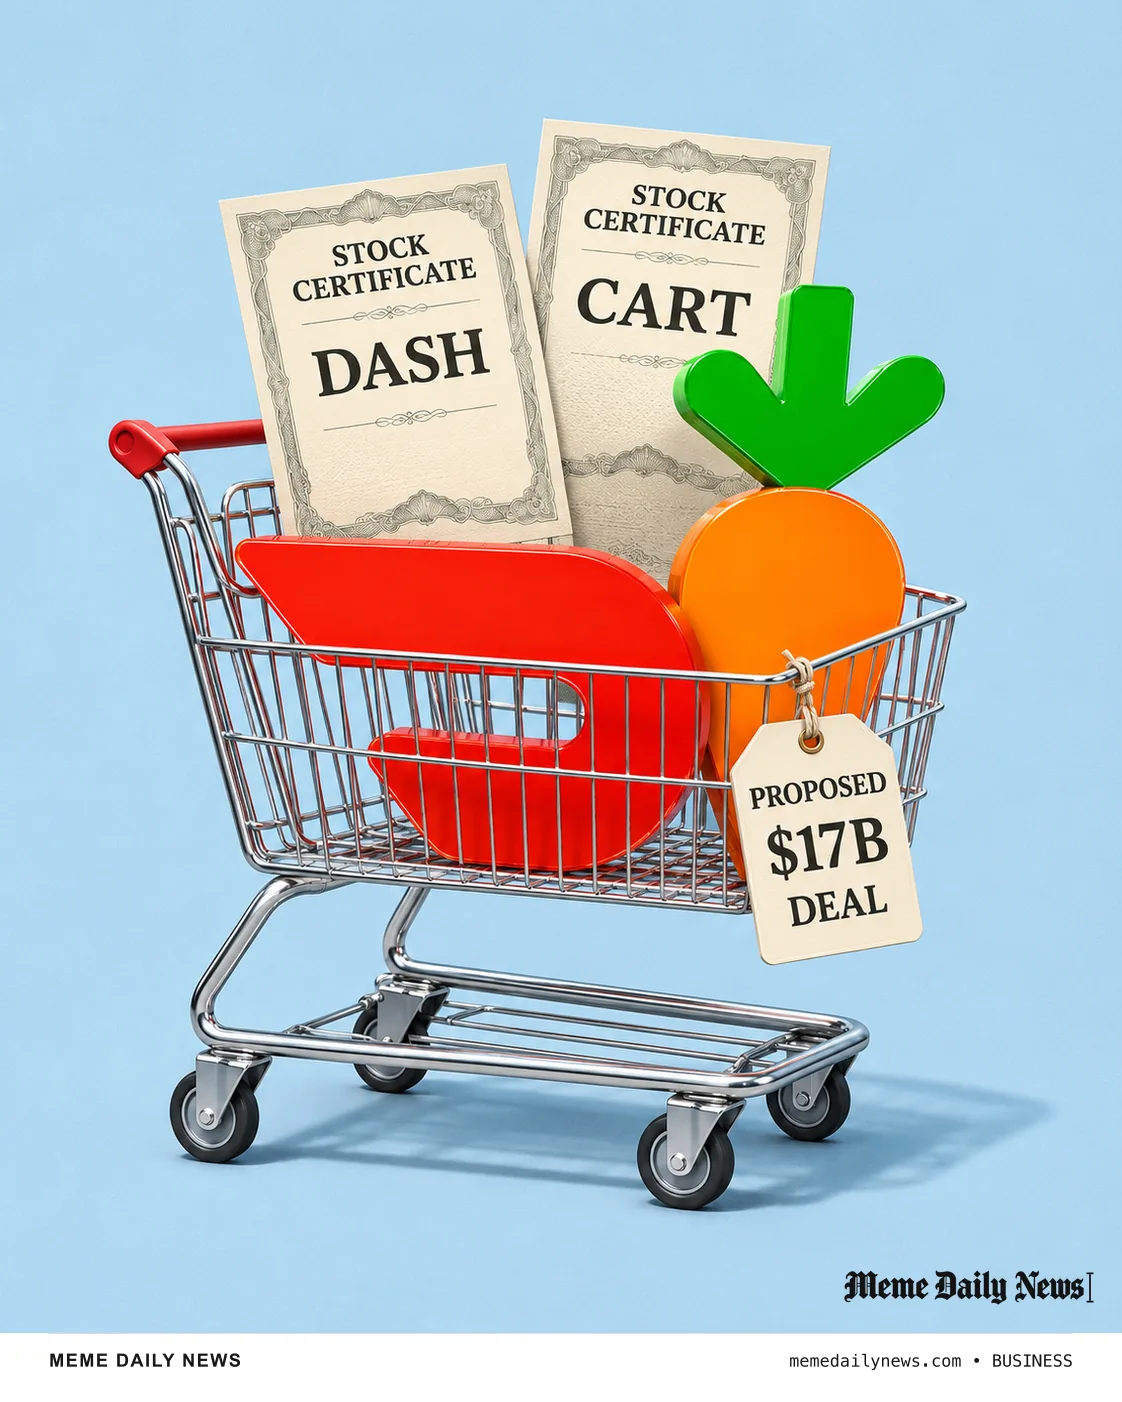
DoorDash puts Instacart in its $17 billion cart
The proposed deal would pair restaurant delivery with the weekly grocery shop, with one membership fee for DashPass and Instacart+.

The actual story.
DoorDash has agreed to acquire Instacart in a deal valuing its equity at approximately $17 billion. The deal was announced October 29. The agreement values each Instacart share at $65, a 26% premium to its October 22 closing price, before reports of a possible transaction.
Instacart shareholders can choose among three payment options. Shareholders can elect $65 cash, 0.3372 DoorDash shares, or $48.75 cash plus 0.0843 DoorDash shares. Across the deal, stock is capped at 25% of consideration, so shareholder choices can be prorated. This is a cash-heavy acquisition, not an all-cash one.
For customers, the headline perk is the subscription bundle. DoorDash says DashPass and Instacart+ members would pay one membership fee instead of two. It also expects to retain Instacart’s brand, app and enterprise products after closing. For now, the businesses remain separate.
The business logic reaches behind the checkout screen. Instacart brings grocery technology and retailer relationships; DoorDash brings its delivery network. DoorDash also commits to letting grocers use competing delivery platforms after the deal closes.
DoorDash’s investor materials explain the operational bet: more grocery volume could spread the fixed costs of inventory management across more orders. The company sees a multiyear path to at least $500 million in annual synergies, net of investments, but expects to reinvest more than all the synergies in the first year after closing.
That gives the subscription offer a strategic role: combining two recurring shopping habits could give customers another reason to stay inside the same delivery ecosystem. This is editorial inference, not a company forecast.
Closing is expected at the end of 2027 or in the first half of 2028, subject to Instacart shareholder approval, U.S. antitrust clearance requirements, regulatory approvals including Canada and Israel, and other closing conditions. The proposed membership savings are not available benefits today.
Dinner tonight. Groceries tomorrow. DoorDash wants to own both habits. Combining DashPass and Instacart+ gives customers a reason to keep paying for one membership—and fewer reasons to open a competitor’s app. The question is whether one subscription means a smaller total bill, or just more spending in one place.
Receipts, not rumors.
Read the original reporting: DoorDash / SEC filing
The reporting above provides context. Illustrations are editorial interpretations, not source photographs.
What’s your take?